Line of business, not individual members
The organization must advance a whole industry or profession. Providing particular services to particular members is the most common reason applications are refused.
Tax-Exempt Formation
A 501(c)(6) is the section for business leagues, trade associations, chambers of commerce, and professional societies — organizations that advance the shared interests of an industry or profession rather than running a business themselves.
See pricing and what’s included
“We were so grateful for Breanna’s work for our small non-profit. Kind, clear, and reliable!”
A prospective client may not obtain the same or similar results.
Already decided? Pay and get started
Tell us about your association. We usually reply the same business day.
Book a free 30-minute callOur team will be in touch shortly. If you would rather pick a time now, book a consultation directly.
Book a ConsultationLegacy Path Law focuses on nonprofit, business, and intellectual property law. Your matter is handled by an attorney — not simply an online filing platform.
The attorneys who will handle your matter
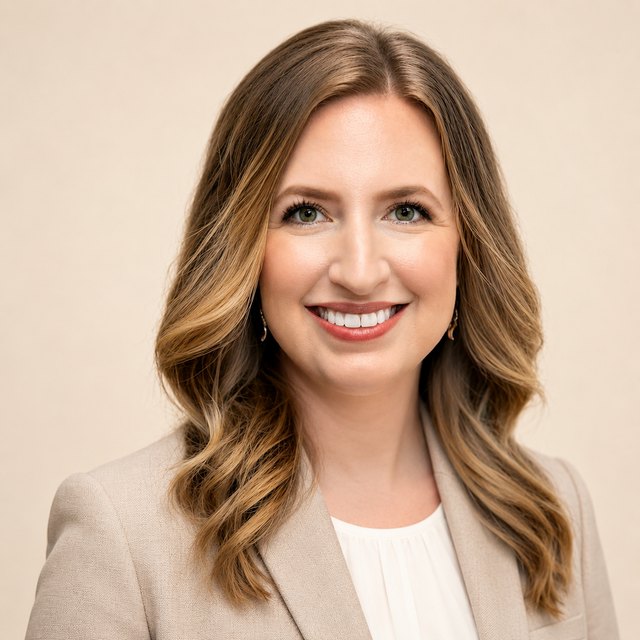
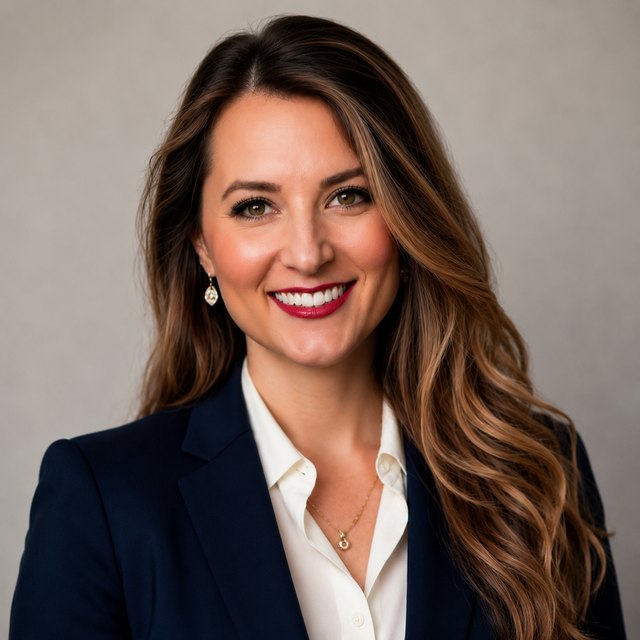
Founding partners Breanna McCarthy and Channing Thomas work in nonprofit and tax-exempt law every day. Breanna is a member of The Florida Bar; Channing is a member of the Virginia State Bar and clerked at the North Carolina Court of Appeals and the Supreme Court of Virginia.
Your matter is handled by an admitted attorney, not an intake team and not a filing service.
501(c)(6) Formation
Flat fee • state filing fees included • no surprise add-ons
Already know which package you want? Pay and get started
Section 501(c)(6) covers business leagues, chambers of commerce, real estate boards, boards of trade, and professional football leagues. The common thread is an organization improving conditions in one or more lines of business, as distinct from performing services for individual members.
That distinction does real work. An association that promotes an industry generally qualifies. One that primarily provides services members would otherwise buy for themselves generally does not.
Member dues are not deductible as charitable contributions. They may be deductible as ordinary business expenses, but the portion attributable to lobbying is not — and the organization must either notify members of that non-deductible percentage or pay a proxy tax on it.
Forming a nonprofit is two separate jobs: creating the entity under state law, and obtaining federal tax exemption from the IRS. Cheaper routes usually cover the first and leave you the second, which is the part where mistakes are expensive to undo.
| Feature | Do It Yourself | Online Filing Service | Full-Service Law Firm |
|---|---|---|---|
| Cost | Lowest upfront cost | Moderate, with add-on fees | Flat fee, agreed in writing |
| State incorporation | You prepare and file | Filed from a template | Attorney-prepared and filed |
| IRS-required language | Commonly missed | Generic boilerplate | Drafted for your purpose |
| Form 1023 or 1023-EZ | You decide and file | Often an upsell | Eligibility assessed, then filed |
| Bylaws & conflict policy | Downloaded templates | Templates, if included | Drafted for your organization |
| Board composition | No guidance | No guidance | Reviewed against IRS expectations |
| IRS follow-up questions | Handled on your own | Additional fees to assist | Responses included |
| Best for | Experienced founders | Simple, low-budget filings | Getting it right the first time |
Amending organizing documents after filing costs more than drafting them correctly, and a denied application means paying the IRS user fee again.
The line-of-business test and the particular-services trap decide most 501(c)(6) applications. Both are addressed in the drafting, not afterwards.
We work out how the organization benefits the trade as a whole, because that framing runs through the articles, the narrative, and the activities.
Articles and bylaws with 501(c)(6) purpose language, membership criteria, and the governance documents the IRS expects to see.
Federal EIN and the recordkeeping structure for dues, events, and any non-dues revenue you expect to generate.
Prepared and submitted through Pay.gov, with the activity narrative and financial projections, and we handle IRS follow-up questions.
A 501(c)(6) exists to improve conditions in a line of business. The line between that and performing services for individual members is where exemptions are won and lost.
You represent an industry, not a company.
The benefit runs to individuals rather than an industry.
Dues are not charitable contributions. Where the organization lobbies, members must receive a notice of the non-deductible portion or the organization pays a proxy tax.
The issues that most often cause trouble later, addressed at the start.
The organization must advance a whole industry or profession. Providing particular services to particular members is the most common reason applications are refused.
If the association lobbies, it must tell members what share of their dues is non-deductible, or pay a proxy tax on those expenditures. Getting this process in place at formation avoids retrofitting it later.
Trade shows, publications, and advertising revenue each have their own treatment. Structuring them correctly at the outset avoids unexpected tax on activities you assumed were covered.
These categories overlap more than they look like they do, and the wrong choice is expensive to unwind. Tell us what your organization actually does and we will tell you which section fits — before you pay for anything. Ask us first.
Not as charitable contributions. Dues may be deductible as a business expense, except for the portion attributable to lobbying, which must be disclosed to members or covered by a proxy tax.
A 501(c)(3) serves a charitable, educational, or similar public purpose and can receive deductible donations. A 501(c)(6) advances the shared business interests of its members and cannot.
Yes. Chambers of commerce, boards of trade, and real estate boards are expressly contemplated by Section 501(c)(6).
The testimonials on this page reflect the experience of those individual clients. Every matter is different, and a prospective client may not obtain the same or similar results.
Flat fee, state filing fees included, and a clear answer on whether 501(c)(6) is the right section before any work begins.
Already decided? Pay and get started