Form 8976 within 60 days
A 501(c)(4) must electronically notify the IRS of its intent to operate within 60 days of formation. This is separate from any application for recognition, and missing it carries penalties.
Tax-Exempt Formation
A 501(c)(4) is built for organizations whose purpose is promoting social welfare — civic leagues, community associations, and advocacy groups. The trade-off is deliberate: you gain far more freedom to lobby than a 501(c)(3) has, and you give up tax-deductible donations.
See pricing and what’s included
“We were so grateful for Breanna’s work for our small non-profit. Kind, clear, and reliable!”
A prospective client may not obtain the same or similar results.
Already decided? Pay and get started
Tell us about your organization. We usually reply the same business day.
Book a free 30-minute callOur team will be in touch shortly. If you would rather pick a time now, book a consultation directly.
Book a ConsultationLegacy Path Law focuses on nonprofit, business, and intellectual property law. Your matter is handled by an attorney — not simply an online filing platform.
The attorneys who will handle your matter
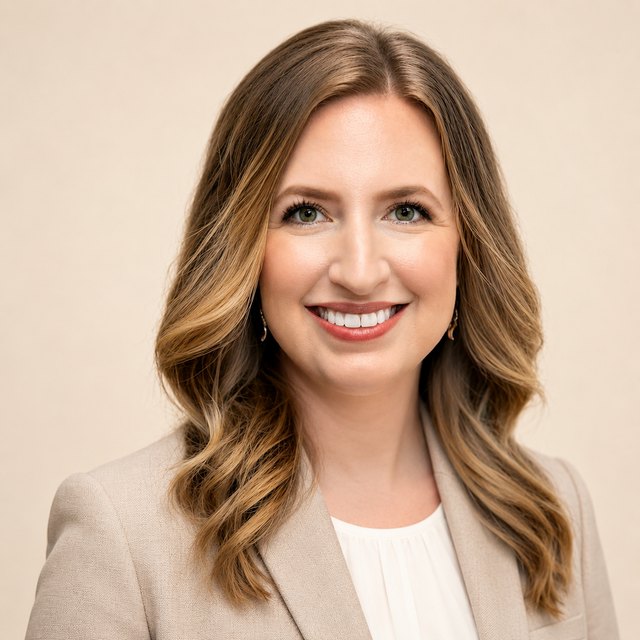
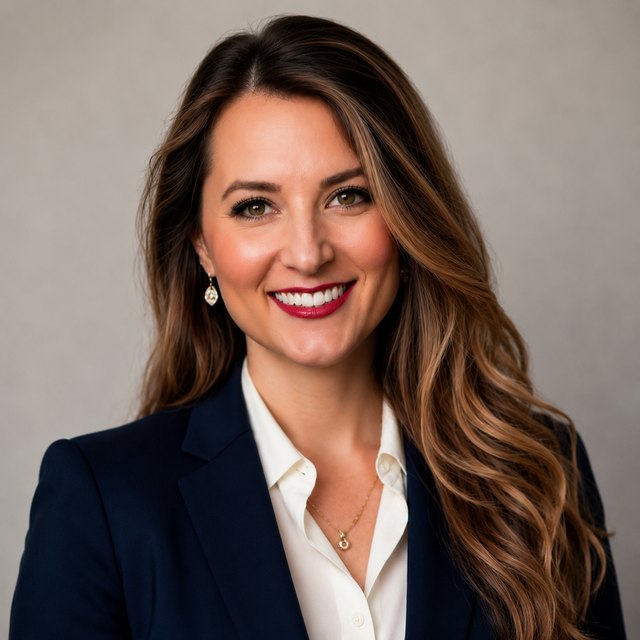
Founding partners Breanna McCarthy and Channing Thomas work in nonprofit and tax-exempt law every day. Breanna is a member of The Florida Bar; Channing is a member of the Virginia State Bar and clerked at the North Carolina Court of Appeals and the Supreme Court of Virginia.
Your matter is handled by an admitted attorney, not an intake team and not a filing service.
501(c)(4) Formation
Flat fee • state filing fees included • no surprise add-ons
Already know which package you want? Pay and get started
Section 501(c)(4) covers civic leagues and organizations operated exclusively for the promotion of social welfare — meaning the common good and general welfare of the community, rather than the private benefit of members.
The practical appeal is advocacy. A 501(c)(4) may lobby without the limits that constrain a public charity, and may engage in some political campaign activity provided it is not the organization’s primary activity. Many advocacy groups pair a 501(c)(3) with an affiliated 501(c)(4) for exactly this reason.
Contributions to a 501(c)(4) are not tax-deductible as charitable donations. If your funding model depends on donors claiming a deduction, this is the wrong section and it is better to learn that now than after formation.
Forming a nonprofit is two separate jobs: creating the entity under state law, and obtaining federal tax exemption from the IRS. Cheaper routes usually cover the first and leave you the second, which is the part where mistakes are expensive to undo.
| Feature | Do It Yourself | Online Filing Service | Full-Service Law Firm |
|---|---|---|---|
| Cost | Lowest upfront cost | Moderate, with add-on fees | Flat fee, agreed in writing |
| State incorporation | You prepare and file | Filed from a template | Attorney-prepared and filed |
| IRS-required language | Commonly missed | Generic boilerplate | Drafted for your purpose |
| Form 1023 or 1023-EZ | You decide and file | Often an upsell | Eligibility assessed, then filed |
| Bylaws & conflict policy | Downloaded templates | Templates, if included | Drafted for your organization |
| Board composition | No guidance | No guidance | Reviewed against IRS expectations |
| IRS follow-up questions | Handled on your own | Additional fees to assist | Responses included |
| Best for | Experienced founders | Simple, low-budget filings | Getting it right the first time |
Amending organizing documents after filing costs more than drafting them correctly, and a denied application means paying the IRS user fee again.
A 501(c)(4) has an extra early deadline most founders have never heard of, and recognition from the IRS is optional rather than required. Both change the order of operations.
We check that social welfare is genuinely your primary purpose. If a 501(c)(3) or a (c)(6) fits better, we say so before anything is filed.
Articles of incorporation and bylaws drafted with 501(c)(4) purpose language, plus the governance policies that keep the lobbying and campaign lines clear.
Filed within 60 days of formation. It is a short electronic notice with a real penalty attached, and it is separate from any application for recognition.
Form 1024-A is optional. Where a determination letter matters to your funders or your state, we prepare and submit it and handle the correspondence.
A 501(c)(4) trades deductible donations for political freedom. That trade is the whole decision, and it is worth making deliberately rather than discovering later.
Advocacy is the point, not a side activity.
Your funding model depends on deductibility.
The Form 8976 notice is due within 60 days of formation, with a daily penalty for late filing. That deadline is the first thing we calendar.
The issues that most often cause trouble later, addressed at the start.
A 501(c)(4) must electronically notify the IRS of its intent to operate within 60 days of formation. This is separate from any application for recognition, and missing it carries penalties.
Unlike a 501(c)(3), a 501(c)(4) may self-declare. Many still file Form 1024-A for a determination letter, because banks, funders, and state regulators frequently ask for one.
Some campaign intervention is permitted, but it cannot be the primary activity, and it may trigger tax consequences. This is the area where 501(c)(4)s most often get into difficulty.
These categories overlap more than they look like they do, and the wrong choice is expensive to unwind. Tell us what your organization actually does and we will tell you which section fits — before you pay for anything. Ask us first.
Generally not as charitable contributions. Some payments may be deductible as business expenses in narrow circumstances, but donors should not expect a charitable deduction.
Yes, and this is often the reason organizations choose it. A 501(c)(4) may lobby without the expenditure limits that apply to public charities, provided the lobbying furthers its social welfare purpose.
Yes. Organizations intending to operate under 501(c)(4) must submit the electronic notice within 60 days of formation, regardless of whether they later seek formal recognition.
The testimonials on this page reflect the experience of those individual clients. Every matter is different, and a prospective client may not obtain the same or similar results.
Flat fee, state filing fees included, and a clear answer on whether 501(c)(4) is the right section before any work begins.
Already decided? Pay and get started